Full text
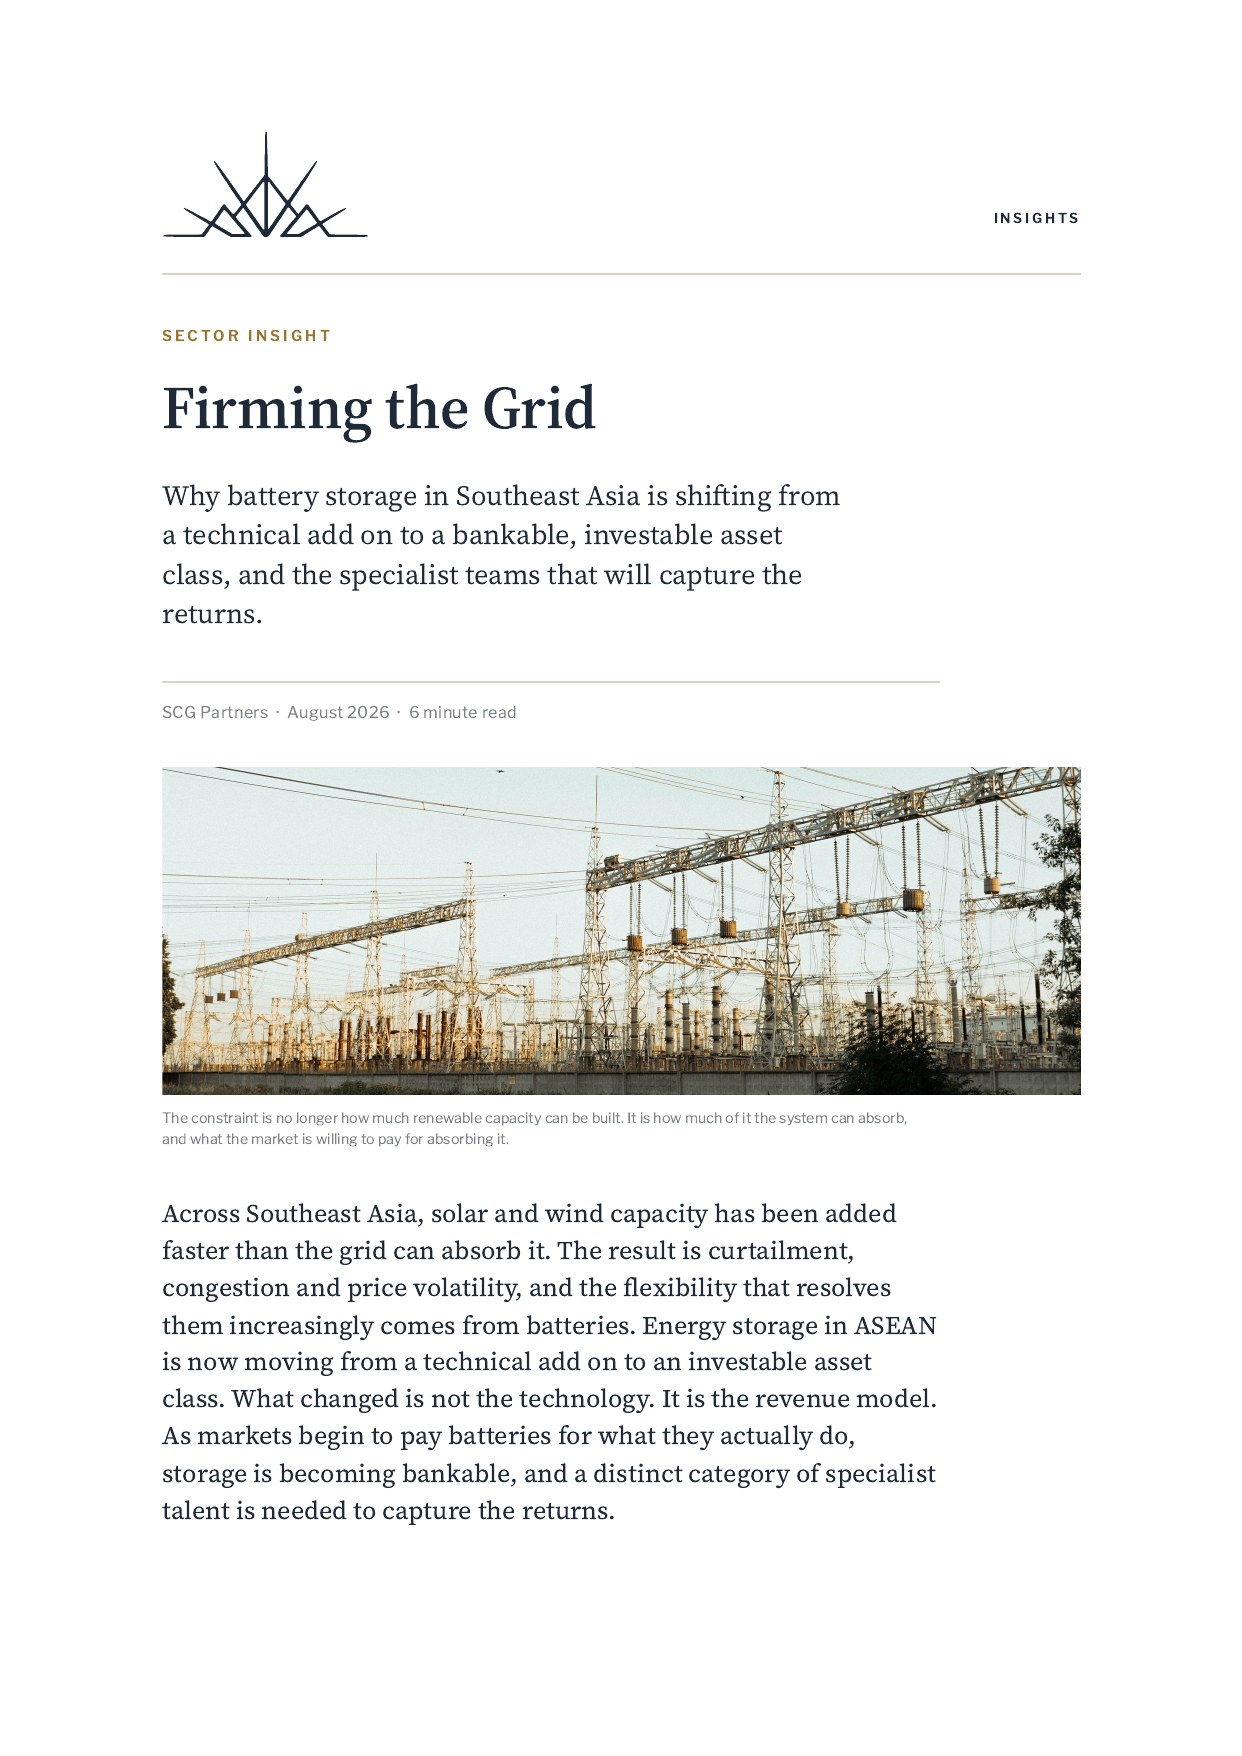
The constraint is no longer how much renewable capacity can be built. It is how much of it the system can absorb, and what the market is willing to pay for absorbing it.
Across Southeast Asia, solar and wind capacity has been added faster than the grid can absorb it. The result is curtailment, congestion and price volatility, and the flexibility that resolves them increasingly comes from batteries. Energy storage in ASEAN is now moving from a technical add on to an investable asset class. What changed is not the technology. It is the revenue model. As markets begin to pay batteries for what they actually do, storage is becoming bankable, and a distinct category of specialist talent is needed to capture the returns.
Why storage, and why now
The scale of the shift is visible in the capital it will take. Investment in the region's grids and storage needs to rise from around USD 13 billion today to about USD 50 billion a year by 2050 to meet announced pledges, and storage sits at the centre of that figure rather than at its edge. The projects already built make the point. In Singapore, the Sembcorp system on Jurong Island, the largest energy storage facility in Southeast Asia, met the country's 200 megawatt hour target two years early and was expanded in 2025 from 285 to 326 megawatt hours by stacking batteries on the same land, the first vertical expansion of an operating system of its kind.
In Indonesia, hybrid plants pairing solar with very large batteries are being developed specifically to export clean, firm power to Singapore, among them the TotalEnergies and RGE project in Riau and a 900 megawatt solar and 1.2 gigawatt hour storage scheme led by Equator Renewables Asia. Storage is no longer a supporting technology. It is becoming the product itself.
From energy only to value stacking
For most of the past decade, battery energy storage systems (BESS) in ASEAN were confined to a single revenue stream that rarely covered their cost. That is the main reason storage stalled while solar surged. What is changing is that markets are beginning to pay BESS for the several services they provide at the same time, the principle known as value stacking.
A battery earns its return from the market it sits in. Where the rules pay for a single service, the asset stays marginal whatever the technology can do.
Vietnam has set the regional benchmark. Its Circular 62, in force from January 2026, is the first standardised pricing framework for standalone, grid scale BESS in a major ASEAN economy, and the first to introduce a two part tariff that pays BESS both a capacity charge for being available and an energy charge for what it discharges. It sits behind a revised national plan that lifted the 2030 storage target from 300 megawatts to between 10,000 and 16,300 megawatts, and a rule requiring certain solar projects to add storage worth at least 10 percent of their capacity for a minimum of two hours. The importance lies not in the target but in the fact that a lender can now underwrite the revenue.
A PRIMER · HOW A BATTERY EARNS ITS RETURN
- ENERGY ARBITRAGE: Charging when power is cheap or in surplus, and discharging when it is scarce or expensive.
- CAPACITY AND AVAILABILITY: Payment for standing ready to deliver, whether or not the battery actually discharges.
- ANCILLARY SERVICES: Fast response that stabilises the grid, such as frequency regulation and operating reserves.
- FIRMING AND AVOIDED CURTAILMENT: Absorbing renewable output that would otherwise be spilled, and returning it as firm supply.
In mature markets a single battery captures several of these streams at once. Most ASEAN markets have historically allowed only one, which is why storage lagged. The regulatory shift now under way is what turns a marginal asset into a bankable one.
The revenue model is becoming financeable. The people who can model it, engineer it and underwrite it are scarcer than the capital behind it.
Targets do not move capital. Bankable revenue models do.
The opportunity, market by market
The mechanism, and therefore the return, differs sharply from one market to the next. A storage business has to be built around the value the local system actually pays for.
WHERE THE RETURNS SIT
- Vietnam: Two part tariff for standalone BESS under Circular 62, plus a solar plus storage mandate. The return sits in capacity payments for availability alongside energy and arbitrage. A defined, financeable revenue base.
- Singapore: Energy Market Authority (EMA) contracted storage, with frequency regulation and grid inertia services in trial. The return sits in contracted revenue plus emerging grid service value. Scarce land rewards density and innovation.
- Indonesia: Solar plus storage export projects feeding firm power to Singapore. The return sits in long term offtake on firm, exported power, underpinned by very large paired storage volumes.
- Philippines: Storage paired with solar through the Green Energy Auctions. The return sits in auction backed offtake, with a growing merchant and ancillary services opportunity.
The commercial route differs in every market, and so does the knowledge needed to deliver there. SCG Partners supports developers and investors entering Singapore and expanding across Asia Pacific with market intelligence, local expertise and the strategic introductions that shorten the path from ambition to a first project.
The specialists a bankable battery needs
A bankable revenue model is necessary, but it does not run the asset or capture the value on its own. That takes a specific and scarce set of skills, and it is where storage projects most often slow down.
Four capabilities matter most, and each is an emerging specialism where the pool of people who have done the work in an ASEAN context is small.
- 01 Revenue and dispatch modelling. Optimises how a system bids across the available value streams, and underpins the investment case.
- 02 BESS engineering and safety. Thermal management, fire risk, degradation and augmentation across a fifteen year asset life.
- 03 Commercial and origination. Structures tolling agreements, capacity contracts and offtake around unfamiliar new mechanisms.
- 04 Project finance. Underwrites a revenue model that, across most of the region, has little or no track record.
This is precisely the kind of scarce, specialist hiring where sector knowledge decides the outcome. SCG recruits these professionals across the energy transition and assesses them on judgement and commercial understanding rather than keywords, because in storage the gap between a strong and a weak hire rarely shows on a CV.
Turning the opportunity into a team
Building a storage business here is as much a talent challenge as an engineering one. SCG Partners works with developers, funds and technology providers across the Asia Pacific energy transition, and supports them in three connected ways.
WORKING WITH SCG
- Finding revenue modellers, BESS engineers, safety leads and project finance specialists in a shallow talent pool: Find Talent. Specialist recruitment of the project, commercial and engineering professionals storage projects depend on, sourced well beyond the active market.
- Establishing a presence or scaling a storage business in a new ASEAN market: Grow Your Business. Practical advisory for organisations entering Singapore and expanding across Asia Pacific, and strengthening local commercial capability.
- Hiring with confidence for first of a kind roles that carry no local track record: Talent Intelligence Framework. Structured assessment that looks past experience and qualifications to the factors that predict success in an unproven field.
Assessing talent for an unproven field
The decisions organisations make about people are among the most important commercial decisions they will ever make, and in a field as new as grid scale storage, experience and qualifications tell only part of the story. The SCG Talent Intelligence Framework brings structure to those decisions, moving the question from whether a person can do the job to whether they will succeed in this role, in this market, over time. It weighs a broader set of factors:
- CAPABILITY: Technical capability, commercial understanding, leadership potential, communication skills.
- EXPERIENCE: Industry experience, international exposure, project complexity, career progression.
- FIT AND GROWTH: Cultural fit and contribution to long term growth.
For a storage hire, project complexity and commercial understanding usually carry the most weight, because the work is new and the revenue logic is unfamiliar. The method is built to enhance professional judgement, not replace it, and it reflects how SCG works throughout: as an industry specialist and long term commercial partner, not a firm that simply fills vacancies.
It combines industry expertise, structured assessment and market knowledge, and over time it will develop into a broader Talent Intelligence Platform supporting recruitment, workforce planning, succession and leadership assessment. The underlying philosophy does not change. Technology should support better decisions, not make them. Successful organisations are built by understanding not only what people have done, but what they are capable of achieving next.
Storage is becoming bankable. The advantage goes to those who can structure the revenue and build the team to run it.